Financial accounting and management accounting are important in accountancy but serve different functions. What has transpired in a compasny is reported in financial accounting, which is also responsible for reports; at the same time, management accossunting, which is involved in the planning of the company’s future actions and in business decision-making, uses both financial and non-financial information.
Comprehension of the differences between financial and management accounting is key for students in the fields of commerce and accounting as well as for professionals in finance, business and management.
What is Financial Accounting?
Financial accounting is a system which records, classifies, sums up and reports a company’s financial transactions. It also informs external parties of the business’s financial performance and position.
We see that the reports used as common elements in finance are the Income Statement, Balance Sheet, Cash Flow Statement, and Statement of Changes in Equity.
Financial accounting reports are used by:
Investors and shareholders
Creditors and lenders
Government and tax authorities
Regulators
External analysts
Example of Financial Accounting
In the past, we have seen that a company at the end of the fiscal year, which ends on March 31st, prepares its Profit and Loss Account, Balance Sheet, and Cash Flow Statement. These reports go to shareholders, banks, regulators, and government authorities. That is an example of financial accounting, which we use to report the company’s financial performance and position.
Purpose of Financial Accounting
In financial accounting, the main goals are to determine profitability, present standard financial information, show the financial health of a business, support reporting requirements, and improve transparency for investors and lenders.
What is Management Accounting?
Management accounting is responsible for the preparation and analysis of both financial and non-financial information for internal use. This information is used by managers and executives in the processes of planning, budgeting, cost control, performance evaluation, and decision-making.
It is primarily useful for: It is for:
Department heads
Internal decision-makers
Example of Management Accounting
A manager who wants to know the cost structure of a given product, which products are more profitable, or which department should be expanded can see. The company may put together cost reports, budgets, forecasts, and break-even analysis to support such decisions. This is management accounting, which is aimed at internal decision-making.
Purpose of Management Accounting
Management accounting plays a role in the planning of future activities for the business, control of costs, evaluation of performance, identification of issues which may arise, improvement of efficiency, and in the process of making informed operational and strategic decisions.
Between Financial and Management Accounting.
Parameter-Financial Accounting-Management Accounting
Purpose: Reports financial results and position; Supports planning and decision-making.
Users: External stakeholders; Internal management
Nature: Mainly historical; Historical and future-oriented
Reporting that is done at set times, which also includes when management requests it.
Standards: Compliance with current accounting rules; more flexible in-house designed solutions.
Focus Area: Business performance: products, departments, activities, and operations.
Reports of financial statements which include budgets, forecasts, cost reports and variance analyses.
Confidentiality of this may be lost to the public at large. We intend this for internal use only.
Level of detail, which is usually a summary, goes into great depth and analysis.
Decision-making: Primarily reporting-focused; Strongly decision-focused
In basic terms, financial accounting reports on a company’s financial results and position, but management accounting is what we use for managers to prepare and make decisions.
Career Scope and Required Skills
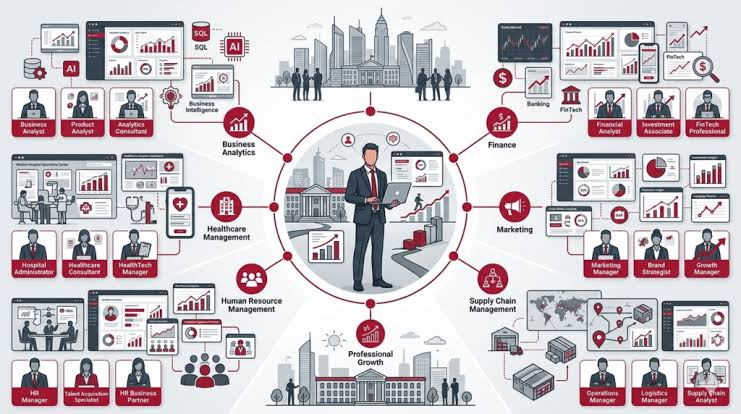
Financial reporting is very much at the core of financial accounting, which also includes accounting, audit, and compliance. In this field, we see roles of financial accountant and auditor, as well as professional qualifications which include CA, ACCA, and CPA.
Management accounting is a field that is very much involved in budgeting, cost analysis, forecasting, performance evaluation, and strategic decision-making. To that end, we see that professionals play these roles in that environment: management accountants and cost accountants, which also includes professionals who have obtained CMA or MBA (Finance) as their qualifications.
Financial accountants usually have knowledge of financial reporting, an in-depth knowledge of accounting standards, accuracy, attention to detail, and compliance. In management accounting, we see that it is more in the realm of strategic planning, cost analysis, business knowledge, analytical thinking, budgeting, and decision-making.
Final Words
Financial accounting and management accounting differ in purpose, users, reporting and application. In financial accounting, we see the structure of a company’s financial performance and position is provided to the external stakeholders. In management accounting, we find that detailed information is made available to internal teams for use in planning, cost control, performance evaluation and decision-making.
In all aspects, we see value in both branches, which play off each other. For students and professionals, we see that what separates them is valuable in building a strong base in accounting and understanding how financial information plays into business operations and decisions.
About the Author