Family Health Insurance in 2026: Why One Policy Might Be Enough for Your Whole House
Nobody plans for a hospital bill. It just shows up — usually at the worst possible time — and suddenly you’re comparing coverage limits at 11 PM instead of sleeping. That’s probably why so many families in India have quietly moved away from buying separate health policies for every member and started putting everyone under a single family plan instead.
So What Is This, Exactly?
A family floater policy does what the name suggests — it lets the sum insured “float” across everyone in the family instead of being locked to one person. Your spouse, your kids, sometimes your parents too, all sit under one policy, one premium, one renewal date. If your son sprains his wrist in March and your mother needs a cardiac procedure in August, both can potentially be paid from the same pool, as long as there’s enough sum insured left to cover it.
It’s less paperwork, fewer due dates to remember, and honestly, one less thing to think about when life is already busy enough.
The Money Side of Things
Here’s the part most people care about first: it’s usually cheaper. Buying four separate policies for a family of four almost always costs more than putting the same four people on one floater plan, because the insurer is spreading the risk across the group rather than pricing each person separately.
Then there’s the tax angle. Premiums paid can get you a deduction under Section 80D — anywhere between ₹25,000 and ₹75,000 depending on who’s covered and their age. Combine that with the savings from a shared premium, and the numbers genuinely start to work in your favour.
Most decent family plans also throw in things individual policies don’t always bother with — a free health check-up once a year, a bonus for not making claims (this either brings your premium down or bumps your coverage up), and the option to “restore” your sum insured if it runs out partway through the year.
What Coverage Should Actually Include
Room rent and basic hospitalisation is the bare minimum — don’t settle for a plan that stops there. A proper family policy should also handle the costs before and after a hospital stay, cover day-care procedures that don’t need an overnight admission, take care of ambulance charges, and ideally leave room for alternative treatments like Ayurveda if that’s something your family uses. A lot of newer plans now include teleconsultation too, so someone can get a doctor’s opinion over a call before deciding whether a hospital visit is even needed.
Before You Actually Buy One
A few things are worth double-checking rather than assuming:
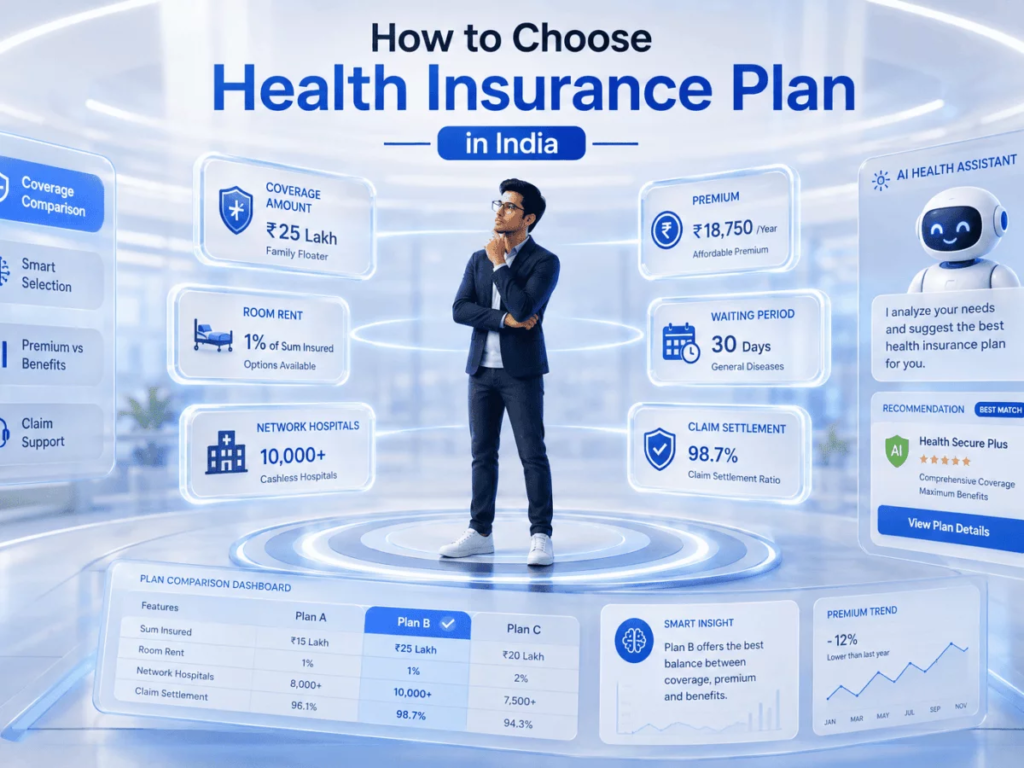
How long is the waiting period, especially for pre-existing conditions? What are the sub-limits — is there a cap on room rent that could leave you paying out of pocket? Does the hospital near your home actually fall under the insurer’s cashless network? And what’s the renewal cut-off age — some insurers stop renewing coverage past a certain point, which can catch families off guard years down the line. Entry rules also matter: most plans want the youngest member to be at least 91 days old, and the oldest usually can’t join after 65.
At the End of the Day
Buying family health insurance isn’t really about the paperwork or the premium comparison spreadsheet. It’s about not having to think twice when someone in your house gets sick. Given how quickly treatment costs are climbing, a well-chosen family plan in 2026 isn’t just a smart financial move — it’s one less worry to carry around.
About the Author